What would improve the case?
Improved monetisation of capital investment; operating cash flow growth; advertising and cloud profitability.
Is growth translating into cash for shareholders?
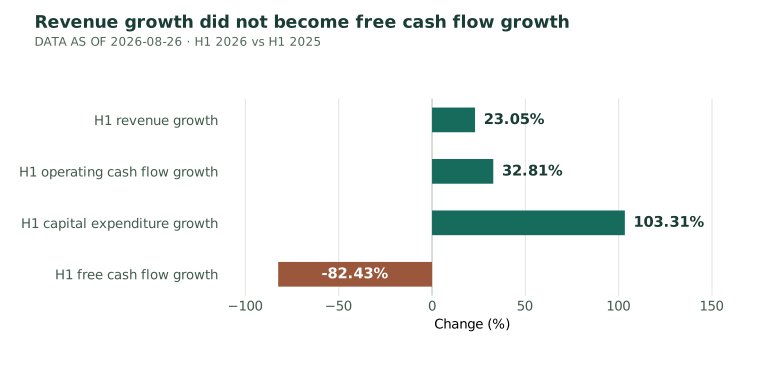
| H1 metric | 2025 | 2026 |
|---|---|---|
| Revenue (USD bn) | 186.662 | 229.692 |
| Operating cash flow (USD bn) | 63.897 | 84.859 |
| Capital expenditure (USD bn) | 39.643 | 80.598 |
| Free cash flow (USD bn) | 24.254 | 4.261 |
Improved monetisation of capital investment; operating cash flow growth; advertising and cloud profitability.
Capital intensity, regulation, AI competition and weaker free cash flow.
My Python workflow, financial analysis and research interpretation.
Financial comparison: H1 2026 vs H1 2025. Historical annualized return in the notebook is the arithmetic daily mean × 252, not CAGR. The old README inconsistently called the YTD end date 18 August and 26 August; this case emphasises fixed-period financial results rather than repeating the ambiguously dated YTD stock return.
Risk-free assumption: 4.64% annual assumption; US 10-year Treasury snapshot, 26 August 2026.
Sources and common conventions →The portable notebook reviews the dated summary inputs offline. The linked original repository contains the full workflow.